# Settings

Configure system preferences, financial settings, and organisational details to match how your body corporate operates.

# Edit settings

You can edit settings by clicking the gear icon on the top right corner:

[![Edit settings.png](https://help.commonview.com/uploads/images/gallery/2025-10/scaled-1680-/VQ4JxvcCTnR62NHj-edit-settings.png)](https://help.commonview.com/uploads/images/gallery/2025-10/VQ4JxvcCTnR62NHj-edit-settings.png)
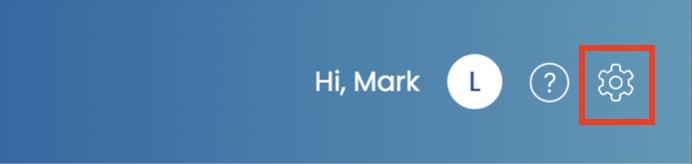
You will be able to change the following:

- [Financial year start](https://help.commonview.com/books/settings/page/financial-year-start "Financial year start")
- [Inflation rate](https://help.commonview.com/books/settings/page/inflation-rate "Inflation rate")
- [Contingency allowance](https://help.commonview.com/books/settings/page/contingency-allowance "Contingency allowance")
- [Interest rate on funds](https://help.commonview.com/books/settings/page/interest-rate-on-funds "Interest rate on funds")
- [Corporate tax rate](https://help.commonview.com/books/settings/page/corporate-tax-rate "Corporate tax rate")
- [Forecast opening balance](https://help.commonview.com/books/settings/page/forecast-opening-balance "Forecast opening balance")
- [Minimum balance](https://help.commonview.com/books/settings/page/minimum-balance "Minimum balance")

# Financial year start

The **Financial Year Start** setting defines the **day and month** when your organisation’s financial year begins.

This setting affects **how years are displayed** in your maintenance plan, ensuring the plan aligns with your financial reporting periods.

---

## How it works

When viewing your maintenance plan, each column represents a financial year.  
The way those years are labelled depends on your selected start date:

- **If your financial year starts on 1 January**  
    The system uses a **calendar year format (YYYY)**.
    
    
    - Example: if the financial year starts on **1 January**, the column will be labelled **2025**.
- **If your financial year starts on any other date**  
    The system uses a **split-year format (YYYY/YY)** to show that the financial year spans two calendar years.
    
    
    - Example: if the financial year starts on **1 April**, the column will be labelled **2025/26** — because the year covers the period from April 2025 to March 2026.

---

## Summary

<div class="_tableContainer_1rjym_1" id="bkmrk-start-date-example-d"><div class="group _tableWrapper_1rjym_13 flex w-fit flex-col-reverse" tabindex="-1"><table class="w-fit min-w-(--thread-content-width)" data-end="1521" data-start="1288"><thead data-end="1343" data-start="1288"><tr data-end="1343" data-start="1288"><th data-col-size="sm" data-end="1309" data-start="1288">Start Date Example</th><th data-col-size="sm" data-end="1326" data-start="1309">Display Format</th><th data-col-size="sm" data-end="1343" data-start="1326">Example Label</th></tr></thead><tbody data-end="1521" data-start="1401"><tr data-end="1437" data-start="1401"><td data-col-size="sm" data-end="1418" data-start="1401">1 January 2025</td><td data-col-size="sm" data-end="1425" data-start="1418">YYYY</td><td data-col-size="sm" data-end="1437" data-start="1425">**2025**</td></tr><tr data-end="1478" data-start="1438"><td data-col-size="sm" data-end="1453" data-start="1438">1 April 2025</td><td data-col-size="sm" data-end="1463" data-start="1453">YYYY/YY</td><td data-col-size="sm" data-end="1478" data-start="1463">**2025/26**</td></tr><tr data-end="1521" data-start="1479"><td data-col-size="sm" data-end="1496" data-start="1479">1 October 2025</td><td data-col-size="sm" data-end="1506" data-start="1496">YYYY/YY</td><td data-col-size="sm" data-end="1521" data-start="1506">**2025/26**</td></tr></tbody></table>

</div></div>> **Note:**  
> This setting does **not** affect calculations or financial values — it only changes how years are **displayed** in your maintenance plan.

# Inflation rate

The **Inflation Rate** setting defines the annual percentage increase applied to future expenses in your maintenance plan.

It helps you account for the rising cost of materials, labour, and services over time — ensuring your forecasts remain realistic and accurate.

---

## How it works

When an expense recurs periodically (for example, every 2, 5, or 10 years), its cost increases by the inflation rate for each year that passes between occurrences.

**Example:**

- Current cost: **$1,000**
- Next due: **2025**
- Frequency: **Every 2 years**
- Inflation rate: **1%**

<div class="_tableContainer_1rjym_1" id="bkmrk-year-calculation-adj"><div class="group _tableWrapper_1rjym_13 flex w-fit flex-col-reverse" tabindex="-1"><table class="w-fit min-w-(--thread-content-width)" data-end="1081" data-start="812"><thead data-end="850" data-start="812"><tr data-end="850" data-start="812"><th data-col-size="sm" data-end="819" data-start="812">Year</th><th data-col-size="sm" data-end="833" data-start="819">Calculation</th><th data-col-size="sm" data-end="850" data-start="833">Adjusted Cost</th></tr></thead><tbody data-end="1081" data-start="891"><tr data-end="923" data-start="891"><td data-col-size="sm" data-end="898" data-start="891">2025</td><td data-col-size="sm" data-end="910" data-start="898">Base year</td><td data-col-size="sm" data-end="923" data-start="910">$1,000.00</td></tr><tr data-end="967" data-start="924"><td data-col-size="sm" data-end="931" data-start="924">2027</td><td data-col-size="sm" data-end="950" data-start="931">$1,000 × (1.01)²</td><td data-col-size="sm" data-end="967" data-start="950">**$1,020.10**</td></tr><tr data-end="1011" data-start="968"><td data-col-size="sm" data-end="975" data-start="968">2029</td><td data-col-size="sm" data-end="994" data-start="975">$1,000 × (1.01)⁴</td><td data-col-size="sm" data-end="1011" data-start="994">**$1,040.60**</td></tr><tr data-end="1055" data-start="1012"><td data-col-size="sm" data-end="1019" data-start="1012">2031</td><td data-col-size="sm" data-end="1038" data-start="1019">$1,000 × (1.01)⁶</td><td data-col-size="sm" data-end="1055" data-start="1038">**$1,061.52**</td></tr><tr data-end="1081" data-start="1056"><td data-col-size="sm" data-end="1062" data-start="1056">...</td><td data-col-size="sm" data-end="1074" data-start="1062">and so on</td><td data-col-size="sm" data-end="1081" data-start="1074">...</td></tr></tbody></table>

</div></div>Each new occurrence uses **compound inflation**, meaning the increase applies cumulatively over time.

---

## Updating the inflation rate

You can update the inflation rate at any time.  
However, changes only affect **future values** — any amounts already approved or recorded for past years remain unchanged.

This allows you to adjust your plan annually (or whenever needed) to better reflect real-world economic conditions.

---

## Summary

- The inflation rate increases **future** expenses based on the number of years until they occur.
- Updates apply **only going forward** — past approved values remain fixed.
- Adjusting the rate periodically helps keep your plan **accurate and realistic** over time.

# Contingency allowance

The **Contingency Allowance** is a percentage added to your total projected expenses to cover **unforeseen or unexpected costs**.

It provides a financial buffer in your maintenance plan, helping you stay on budget even when actual costs are higher than estimated.

---

## How it works

#### how it works

Once all tasks and costs are calculated, the contingency allowance applies as a percentage **on top of the total**.

For example:

- Total planned cost: **$100,000**
- Contingency allowance: **5%**
- Total with contingency: **$105,000**

This additional amount does not correspond to a specific task — it represents a reserve to handle unplanned events such as:

- Emergency repairs
- Unexpected price increases
- Delays or variations in project scope
- Unforeseen maintenance requirements

---

## Adjusting the allowance

You can update the contingency percentage at any time to reflect your organisation’s risk tolerance or financial strategy.

- **A lower percentage (e.g. 2–5%)** may be appropriate for stable, predictable portfolios.
- **A higher percentage (e.g. 10–15%)** may suit older buildings, complex assets, or environments with high uncertainty.

Updating the contingency allowance automatically recalculates your overall projected cost to include the revised buffer.

---

## Summary

- The contingency allowance is a **risk buffer** added to total expenses.
- It helps ensure your budget remains **resilient to unforeseen costs**.
- You can adjust the percentage to match your level of financial caution or project complexity.

# Interest rate on funds

The **Interest Rate on Funds** represents the annual return (in percentage) earned on your maintenance fund balance.

It reflects the interest your organisation receives from the bank or financial institution where your maintenance fund is held.

---

## How it works

Each year, your maintenance fund earns interest based on the **closing balance** of the previous year and the interest rate you specify.

This interest is added to the fund, helping to offset future expenses and keep the plan sustainable over time.

**Example:**

- Opening balance (start of year): **$50,000**
- Interest rate: **2%**
- Interest earned: **$1,000**

Over time, this compounding effect can significantly improve the fund’s long-term health, especially for large or multi-year maintenance plans.

---

## Updating the interest rate

You can update the interest rate at any time to reflect changes in your bank account or investment terms.  
Adjusting the rate recalculates **future balances** but does not alter past years that have already been approved or finalised.

Keeping this rate up to date ensures that the **closing balance** displayed in your maintenance plan remains accurate and aligned with real-world financial conditions.

---

## Summary

- The interest rate represents the **annual return** on your maintenance fund.
- It is used to calculate the **closing balance** for each financial year.
- Updating the rate affects **future projections**, not past approved years.
- Accurate interest rates help keep your plan’s financial forecasts realistic.

# Corporate tax rate

The **Corporate Tax Rate** represents the percentage of tax your organisation pays on the **interest earned** from your maintenance fund.

This setting ensures that your maintenance plan reflects the *net* growth of the fund after tax deductions, providing a more accurate closing balance projection.

---

## How it works

Each year, the system calculates interest on your maintenance fund using the **Interest Rate on Funds**.  
The **Corporate Tax Rate** is then applied to that interest amount to determine how much tax is deducted before it’s added to your balance.

**Example:**

- Fund opening balance: **$50,000**
- Interest rate: **2%** → Interest earned: **$1,000**
- Corporate tax rate: **28%**
- Tax deducted: **$280**
- Net interest added to fund: **$720**

This ensures that the growth of your maintenance fund matches what you would actually expect after taxes are paid.

---

## Updating the tax rate

You can update the corporate tax rate at any time to reflect your organisation’s current tax obligations.  
As with other financial settings, any change affects **future calculations only** — past years that have already been approved remain unchanged.

Keeping this rate accurate ensures that your plan’s **closing balance** and **fund growth** projections remain realistic.

---

## Summary

- The corporate tax rate is applied to **interest earned** from your maintenance fund.
- It ensures your **closing balance** reflects **net (after-tax)** growth.
- Updating the rate affects **future projections** only.
- This setting helps maintain an accurate and compliant financial forecast.

# Forecast opening balance

The **Forecast Opening Balance** represents the projected starting balance of your maintenance fund at the beginning of a financial year.

Because a maintenance plan is a forecast, it cannot perfectly predict the future. Actual balances may differ from what was originally planned. This setting allows you to **update the plan to match the real opening balance** at the start of the financial year.

---

## How it works

At the start of a new financial year, you can enter the **actual opening balance** of the maintenance fund.

This updated balance becomes the starting point for:

- Calculating interest earned during the year
- Deducting maintenance costs
- Updating the closing balance for the year

**Example:**

- Predicted opening balance for 2025: **$50,000**
- Actual balance at the start of 2025: **$52,000**

By updating the forecast opening balance to **$52,000**, all calculations for 2025 and subsequent years will use this actual figure, ensuring that your plan reflects reality as closely as possible.

---

## Key points

- The **forecast opening balance** can be updated **at any time**.
- This ensures your maintenance plan remains **accurate and up-to-date**, even if actual fund balances differ from the original forecast.

---

## Summary

- The forecast opening balance lets you **adjust your plan to reality** at the start of each financial year.
- It ensures that interest, costs, and closing balances are calculated from the **correct starting point**.
- Keeping this value accurate improves the reliability of your maintenance plan over time.

# Minimum balance

The **Minimum Balance** represents the lowest amount you want to keep in your maintenance fund account at any time.

It helps you visualise a safe financial buffer and plan your cash flow accordingly.

---

## How it works

Currently, this setting **does not affect calculations** or prevent spending below the amount set.

- The value is **displayed on the cashflow chart** to show the minimum threshold alongside your projected fund balance.
- This allows you to quickly see if your planned maintenance and other expenditures might bring the fund close to or below this level.

**Example:**

- Minimum balance: **$10,000**
- Projected closing balance: **$12,000**
- Cashflow chart shows the $10,000 line as a reference, so you can see there’s still a safe buffer.

---

## Future functionality

In future releases, the **Minimum Balance** setting will be used to **actively prevent the fund from going below the set amount**, helping you maintain a safer financial position automatically.

---

## Summary

- Minimum balance is a **reference point** to visualise a safe fund level.
- Currently, it **only appears on the cashflow chart**.
- Future updates will allow the system to **enforce the minimum balance**, ensuring the fund never drops below this level.